So, you’re running a small business and things are going well, but have you thought about protecting your hard-earned investment? That’s where small business insurance comes into play. Let’s dive into the fascinating world of small business insurance to discover how it can safeguard your entrepreneurial dream from unforeseen disasters.
From liability to property and everything in between, understanding the range of available insurance policies can be a game-changer for your business. This comprehensive guide will walk you through the types of insurance you need to consider, why they’re crucial for your business’s survival, and how to choose the right coverage. Buckle up because you’re about to become an insurance pro!
Types of Small Business Insurance
Did you know that 40% of small businesses never reopen after a disaster? That’s why having the right insurance is crucial. BUT, what types of insurance do you actually need? Let’s break it down.
Small business insurance is not one-size-fits-all. It comes in various policies, each catering to different risks and needs. Here’s the deal: understanding these can be the difference between staying afloat or going under when disaster strikes.
General Liability Insurance
Every small business should consider general liability insurance. It covers legal costs and damages if you’re found liable for injury or property damage. Imagine a customer slipping in your store—this insurance has you covered.
- Covers bodily injury and property damage liability
- Protection against slander and libel lawsuits
- Optional coverage for product liability
Pro Tip: Always review your policy for specific exclusions and add-ons.
Professional Liability Insurance
Also known as Errors and Omissions (E&O) insurance, this is essential for service-based businesses. It protects against claims of negligence or inadequate work. Picture a consultant giving poor advice that costs their client—E&O insurance steps in here.
- Coverage for alleged mistakes or failure to perform
- Protection against legal defense costs
- Essential for lawyers, consultants, and IT professionals
Pro Tip: Tailor your E&O policy to the specific risks of your industry.
Property Insurance
Does your business own or lease physical space? Then you need property insurance. It covers damage to your building and its contents due to fires, storms, or vandalism. Remember the shocking statistic about disasters? This is where property insurance shines.
- Protection against natural disasters
- Coverage for physical assets like equipment and inventory
- Can include business interruption coverage
Pro Tip: Check if your policy covers floods or earthquakes; you might need a separate policy.
Workers’ Compensation Insurance
If you have employees, this insurance is usually mandatory. It covers medical expenses and lost wages if an employee gets injured on the job. Think about a worker slipping in the warehouse—workers’ comp saves the day.
- Required by law in most states
- Covers employee injuries and rehabilitation costs
- Protection against employee lawsuits over workplace conditions
Pro Tip: Regularly review safety protocols to lower premiums and prevent claims.
Importance of Small Business Insurance
Did you know that 40% of small businesses never reopen after a disaster? It’s shocking but true. This is why insurance is your lifeline.
As a small business owner, you’re exposed to countless risks every day. From a slip-and-fall accident on your premises to a fire that wipes out your inventory, these events can destroy your business in a heartbeat. That’s where insurance comes into play. It provides a safety net that helps you recover and continue operations without facing financial ruin. And trust me, it’s not just about surviving—it’s about thriving even after setbacks.
Mitigating Risks with Adequate Coverage
Here’s the deal: insurance is not a “nice-to-have”—it’s a “must-have.” Without it, you’re essentially gambling with your business’s future. Whether it’s property damage, liability issues, or employee-related risks, adequate insurance coverage can save your business from unexpected financial blows. You’ll sleep better knowing that you have a backup plan that can cover losses and damages when the unexpected happens. And let’s face it, in business, the unexpected is the norm.
Pro Tip: Always evaluate your coverage annually to ensure it aligns with your growing business needs.
Now, think about this: what’s the long-term impact of not having insurance? In a word, closure. Without insurance, a single catastrophic event could force you to shut your doors permanently. You’ll not only lose your source of income but also everything you’ve invested in building your business. It’s a risk you simply can’t afford to take.
Cost Factors for Small Business Insurance
Ever wondered why two businesses in the same industry pay vastly different insurance premiums? It’s not just about luck. It’s about understanding the key factors that affect the cost of your small business insurance.
Let’s dive into how these factors, like business size and industry type, can impact what you’re paying. You might find some surprising insights that can help you save!
Factors Affecting Insurance Cost
Insurance premiums aren’t random. They depend on specific elements unique to your business. For instance, the industry you’re in plays a massive role. A construction business will naturally face higher premiums compared to a florist shop. Why? Because the risk is different!
- Business Size: A larger company typically pays more because there’s more to insure.
- Industry Type: The nature of your business can heavily influence your cost.
- Location: Operating in a high-crime area? Expect to pay more.
- Claim History: Frequent claims? Your premiums will reflect that.
Cost Advantages Across Providers
Not all insurance providers are created equal. Some offer better deals based on specific business attributes. Here’s how you can compare:
| Provider | Strengths | Potential Savings |
|---|---|---|
| Provider A | Great for tech startups | Up to 15% lower for IT businesses |
| Provider B | Focus on retail businesses | 10% savings for low-risk retailers |
Here’s the deal: Don’t just settle for the first quote. Shop around and leverage your business specifics to negotiate better rates.
Impact of Business Size and Industry
Your business size and industry are not just numbers on paper. They directly affect your insurance premiums. A small consultancy firm in a low-risk area will naturally have lower premiums compared to a large manufacturing plant with complex operations.
Pro Tip: Use your business’s low-risk attributes as a bargaining chip to negotiate better rates. Highlight your safety measures and clean claim history!
You see, the key is to understand these factors and use them to your advantage. By doing so, you can secure the best insurance deal tailored to your business needs.
How to Choose the Right Insurance
Did you know that 40% of small businesses never reopen after a disaster? That’s why choosing the right insurance is crucial. It’s not just about having coverage—it’s about having the right coverage.
When it comes to selecting business insurance, the options can be overwhelming. But here’s the deal: you need a strategy to navigate the myriad of policies. Choosing the right insurance isn’t just about cost; it’s about finding the sweet spot between coverage and affordability.
Criteria for Selecting Appropriate Insurance
You need to start with what your business truly requires. Define your risk profile: Are you a retail store, a service provider, or a manufacturer? Different businesses have different needs. For example, a tech startup might prioritize cyber liability, while a construction business would need strong general liability and workers’ comp.
Next, consider the size and scope of your operations. This will influence whether you need additional endorsements or a basic policy. And don’t forget about local regulations—some areas require specific coverage types by law.
Methods to Evaluate Insurance Providers
Not all insurance providers are created equal. Step #1 is to do your homework. Check their customer reviews and ratings from third-party sites. Trustworthy providers should have a track record of good customer service and quick claims processing.
Step #2 is to compare their offerings. Don’t just look at premiums; examine the coverage details. What’s included? What’s excluded? And perhaps most importantly, how do they handle claims?
Pro Tip: Choose a provider with a dedicated small business team. They’ll understand your unique needs better than a general insurer.
Checklist for Assessing Small Business Insurance Needs
Here’s a quick checklist to help you assess what your business might need:
- Identify potential risks specific to your industry and location.
- Evaluate the value of your physical assets like property and equipment.
- Determine if you need additional protection, like business interruption insurance.
- Check if your employees need specific coverage, like health or disability insurance.
- Review your budget and compare it to potential out-of-pocket costs.
By following this checklist, you’ll be well on your way to finding the right coverage. Remember, the goal is to balance protection with cost-effectiveness.
Common Claims and Coverage Gaps
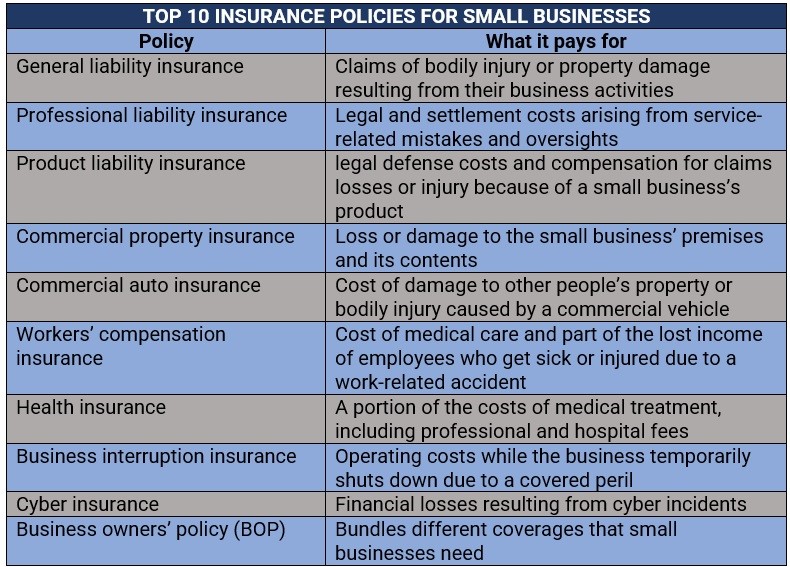
Did you know that nearly half of small businesses will experience an insurance claim in any given year? Yep, that’s right. And the kicker is, many of these claims aren’t fully covered!
Understanding common claims and the coverage gaps that accompany them can make or break your business. But here’s the deal: recognizing these gaps early can save you a boatload of trouble down the line.
Typical Small Business Insurance Claims
Small businesses, regardless of their industry, often encounter a few recurring types of claims. The most common include property damage, customer injuries, and employee-related incidents. Imagine a client slips on a wet floor in your store or a fire damages your inventory. These scenarios aren’t just hypothetical—they happen more often than you might think.
It is crucial to have a comprehensive policy that covers these potential risks. Trust me, you don’t want to learn about a coverage gap when you’re already knee-deep in a claim.
Unseen Coverage Gaps
Even if you think you’re fully covered, there might be hidden coverage gaps lurking in your policy. These can be sneaky and often include exclusions for flood damage, cyber attacks, or certain types of liability. Many small business owners assume they’re protected until they’re not.
Here is the deal: Insurance policies can be tricky, and it’s essential to scrutinize them for any exclusions or limitations that might affect your coverage.
Strategies to Manage Coverage Gaps
So, how do you protect yourself from these gaps? Step #1: Regularly review your insurance policy with a pro who knows their stuff. You need an expert who can point out any areas that may leave you exposed.
Step #2: Consider purchasing additional coverage or endorsements to plug those gaps. It might cost a bit more upfront, but trust me, it’s a small price for peace of mind.
Pro Tip: Always keep your insurer updated about any changes in your business operations. This ensures your policy reflects your current risks.
Legal and Compliance Considerations
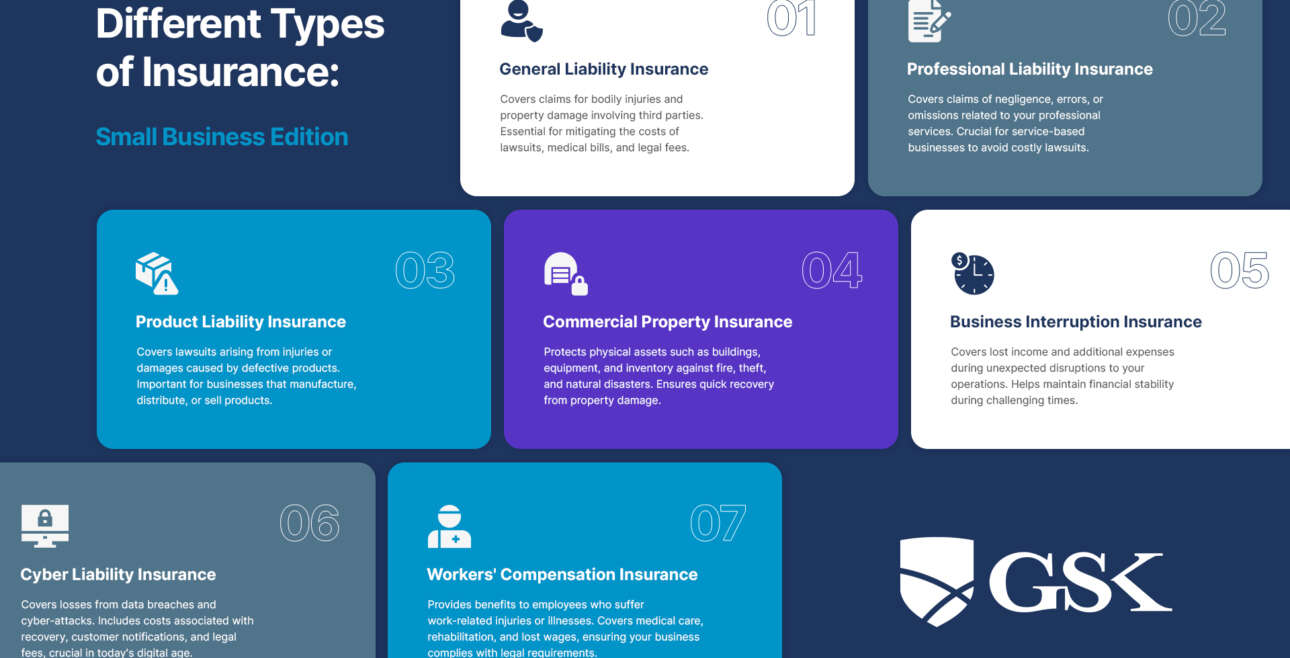
Did you know that a whopping 44% of small businesses have never had insurance? That’s a massive risk. You and I both know that operating without the right insurance can lead to ugly legal problems.
Small business insurance isn’t just a good idea—it’s often a legal requirement. Different regions have different laws about what types of insurance you need. Skipping these can land you in serious hot water.
Understanding Regional Insurance Requirements
The legal landscape for small business insurance can be a minefield. In the U.S., many states mandate workers’ compensation if you have employees. In the UK, employers must have liability insurance. But here’s the deal: missing these requirements doesn’t just mean fines. It means your business is at risk every day.
Compliance Issues Related to Business Insurance
Compliance is not just about buying a policy. It’s about having the right coverage. Say you’re running a tech startup. General liability might not cover your specific tech-related risks. You need cyber insurance. Failing to comply can lead to denied claims and lawsuits. And trust me, nobody wants that!
Real Cases of Non-Compliance Woes
Consider a bakery owner in California who skipped workers’ compensation. One slip and fall led to a lawsuit that nearly bankrupted the business. Compliance isn’t a checkbox. It’s a shield. Another example? A consultant without professional liability got sued over advice gone wrong. Their personal assets were on the line.
Pro Tip: Always review your policies annually or after major business changes to stay compliant and protected.
Summary
In the unpredictable realm of business, insurance is not just a safety net; it’s a crucial ally. By ensuring that your small business is adequately covered, you’re not only protecting your investment but also setting the stage for long-term success. So, dive into the world of small business insurance with confidence, armed with the knowledge to choose the right policies and providers that align with your unique needs. Remember, peace of mind is priceless, and with the right coverage, you can focus on what you do best—growing your business.
Q&A
What are the different types of small business insurance?
Common types include general liability insurance, property insurance, workers’ compensation insurance, and professional liability insurance. Each serves a unique purpose in protecting various aspects of your business.
Why is small business insurance important?
Insurance is crucial as it shields your business from financial losses due to accidents, lawsuits, or natural disasters, ensuring business continuity and peace of mind.
What factors influence the cost of small business insurance?
Factors include the size and industry of your business, the number of employees, the types of coverage you need, and your business location.
How can I choose the right insurance for my small business?
Start by assessing your business risks, compare offerings from multiple providers, and consult with insurance experts to tailor coverage that fits your needs.
What are common claims made by small businesses?
Common claims include slip-and-fall accidents, property damage, and employee injuries. Each type of insurance addresses specific claims to protect your business.
Leave a Reply